
Which Reg E clocks run on a dispute, and where do banks miss them?
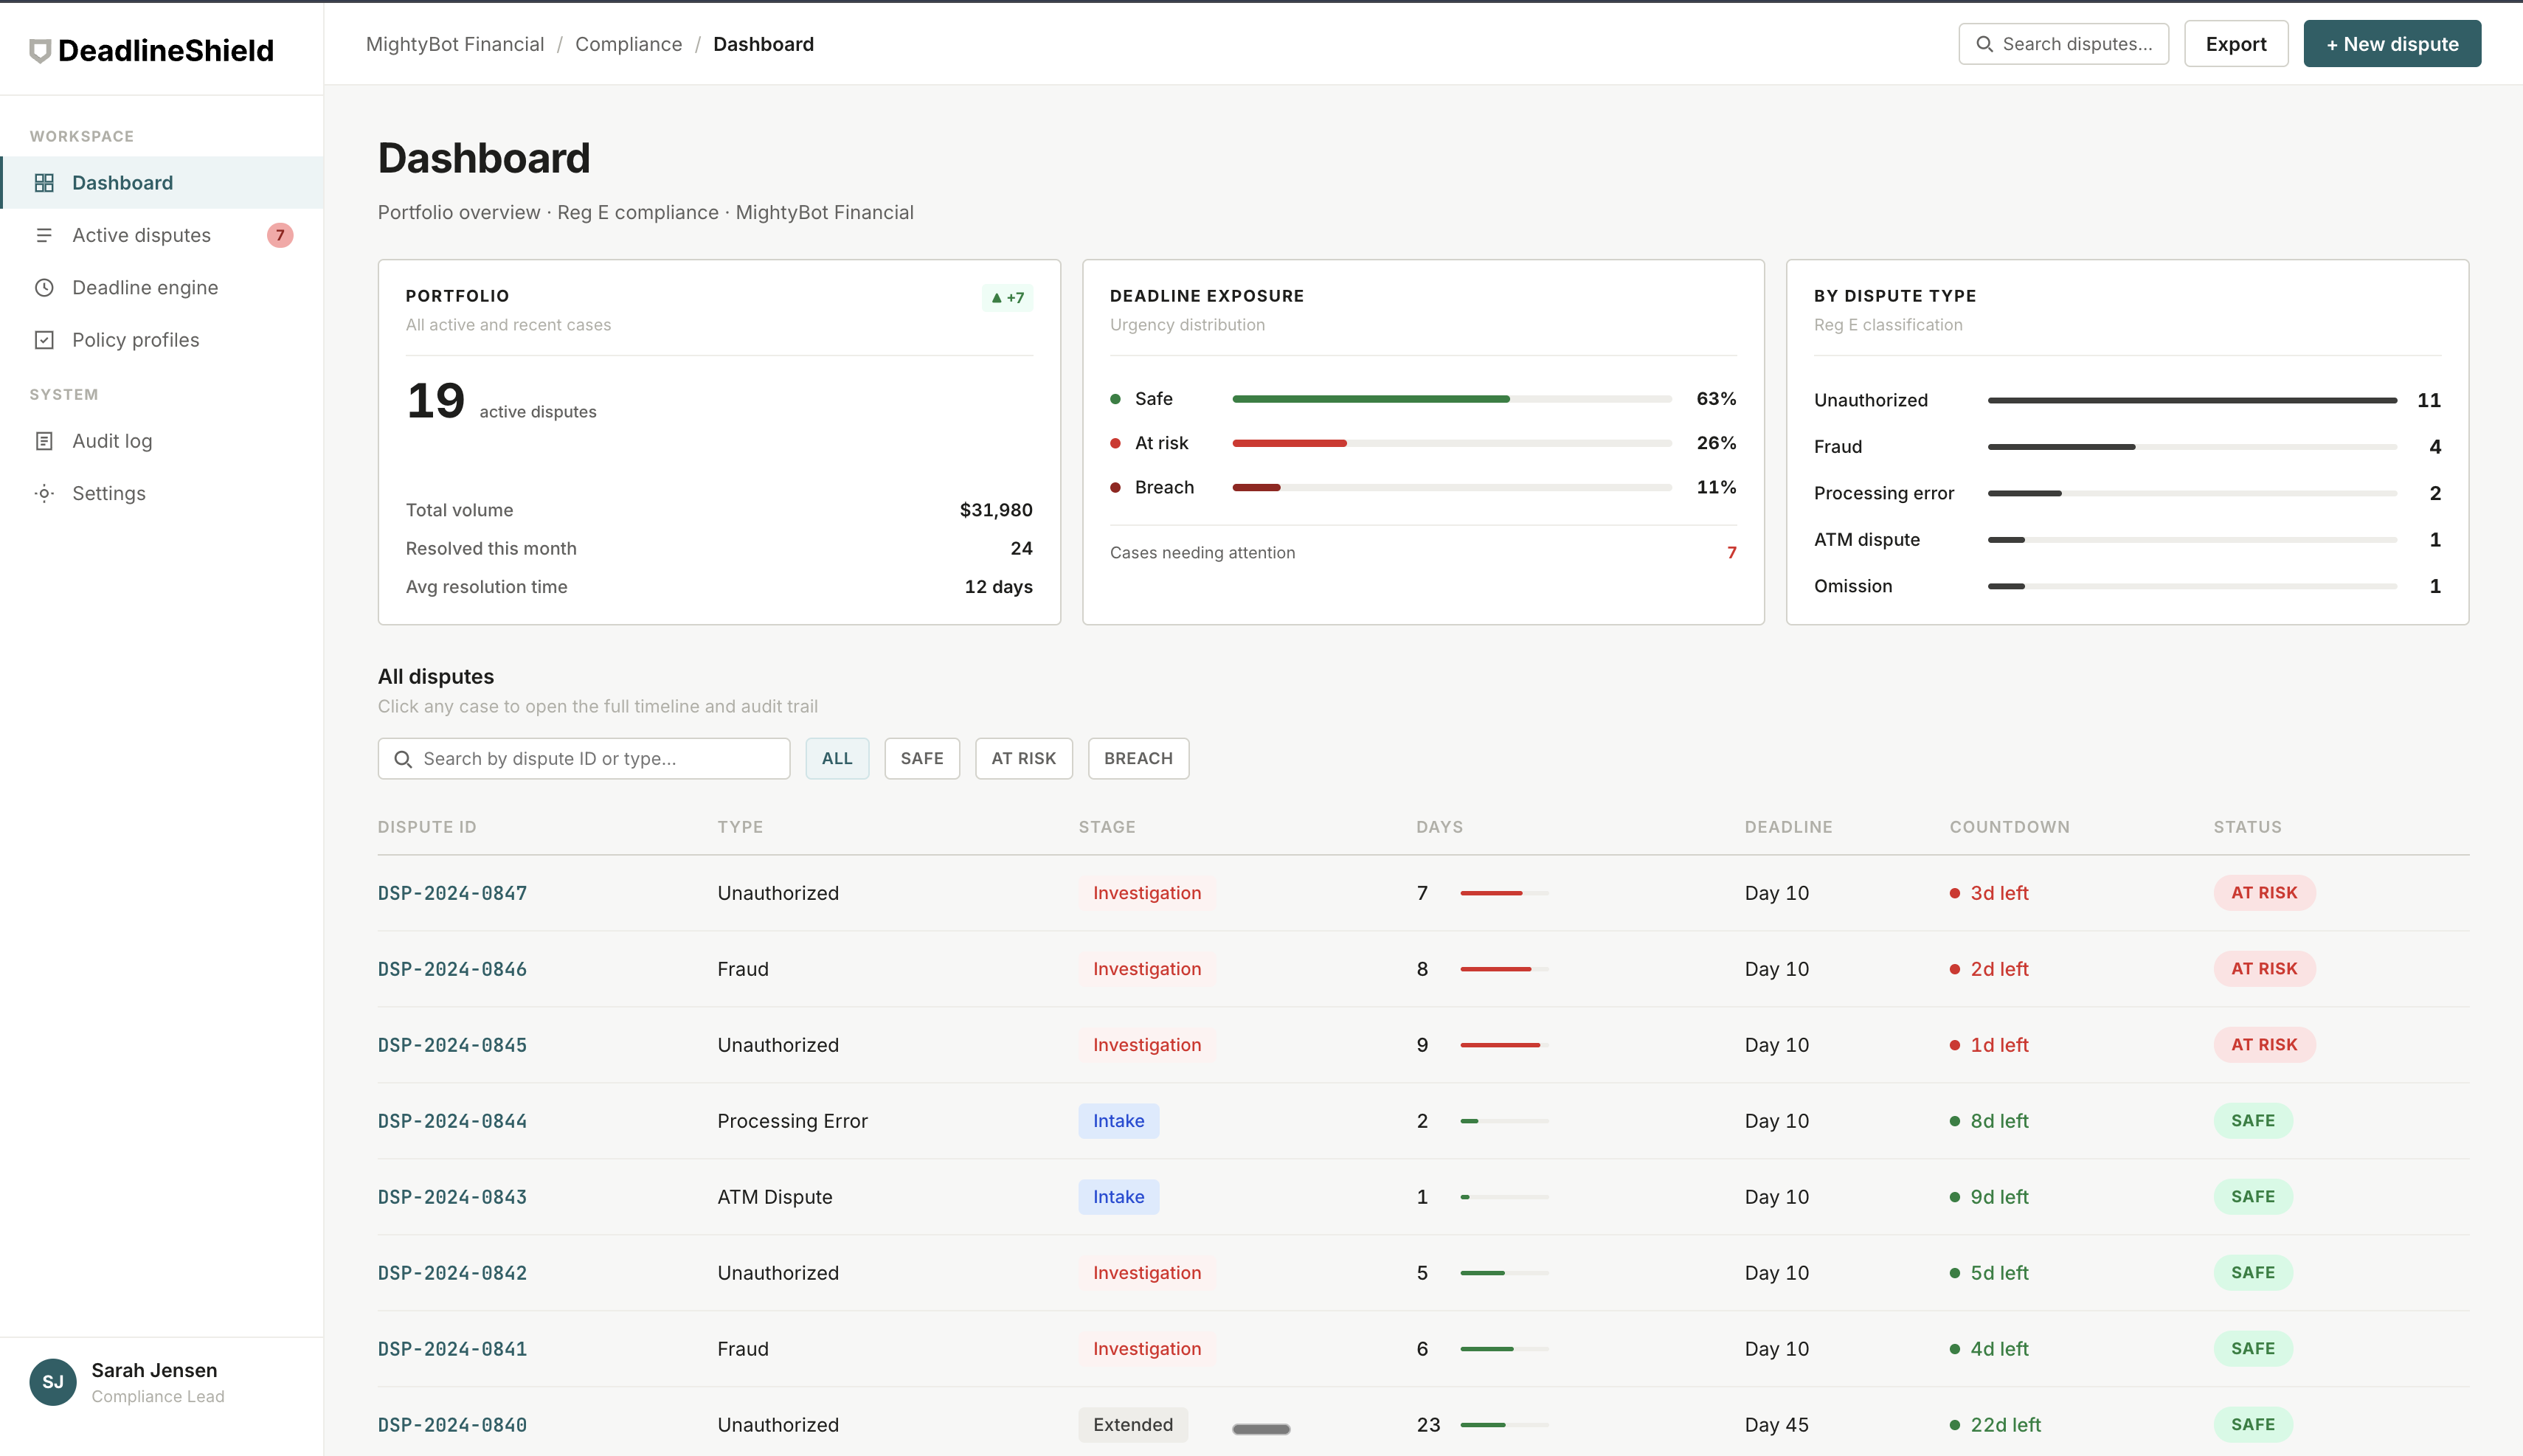
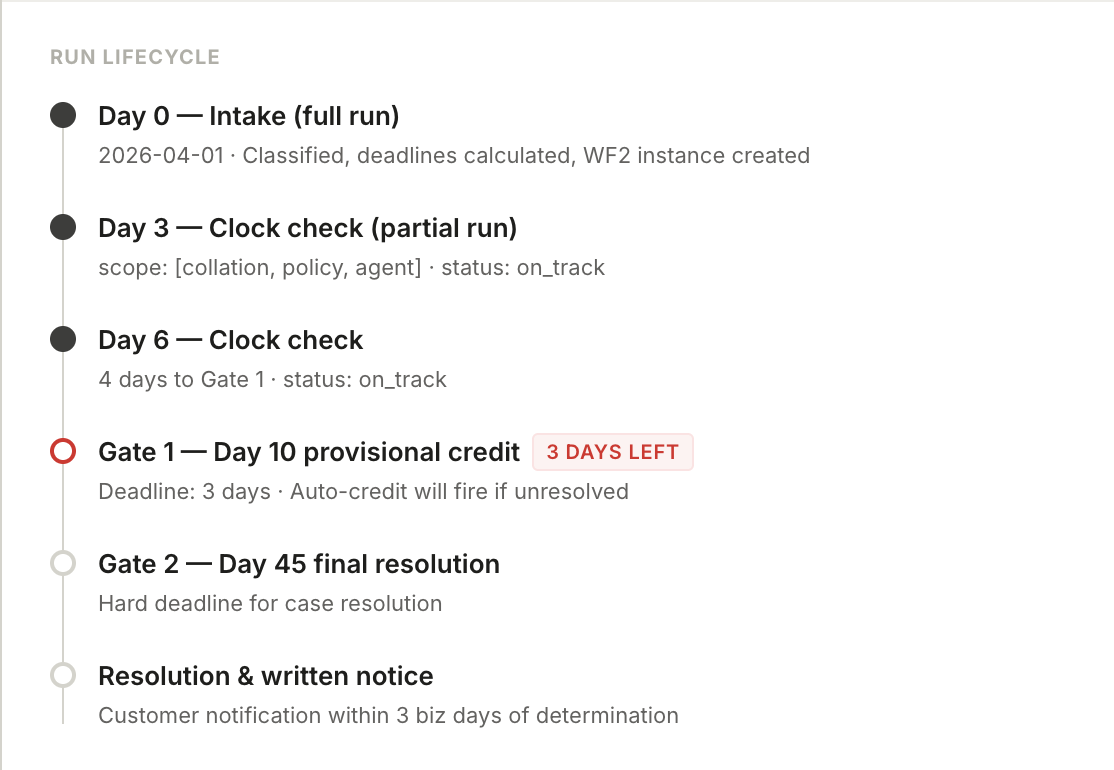
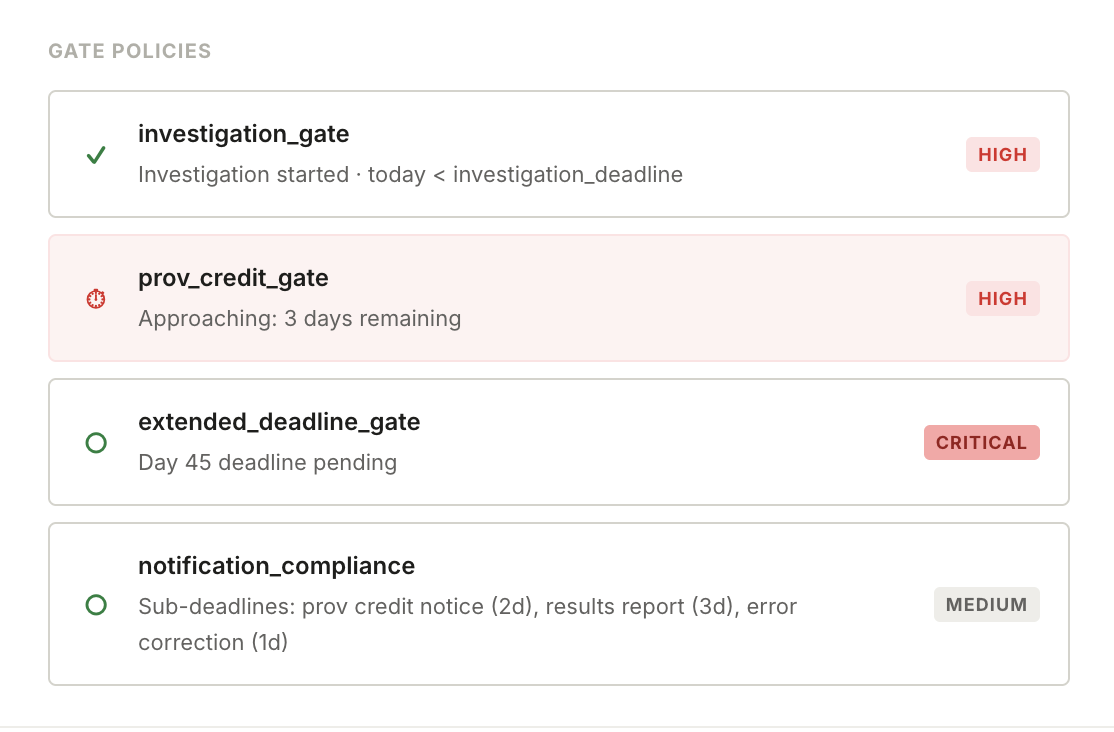
Regulation E gives a bank 10 business days from a notice of error to investigate and determine "whether an error occurred," or "up to 45 days from receipt of a notice of error to investigate and determine" if it provisionally credits the consumer's account. For new accounts, point-of-sale and foreign transactions, "The applicable time is 20 business days in place of 10 business days" and "The applicable time is 90 days in place of 45 days." The consumer has 60 days from the statement to give notice, and records must be kept "not less than two years."
Missing these is common. The Federal Reserve reported that in 2024, Regulation E error-resolution violations "were among the top-cited consumer compliance violations in examinations." One finding: institutions "failed to provide an adequate explanation, using generic language," such as a bare "no error." The article adds, "These violations were the result of insufficient templates generated by the institution's dispute tracking system."
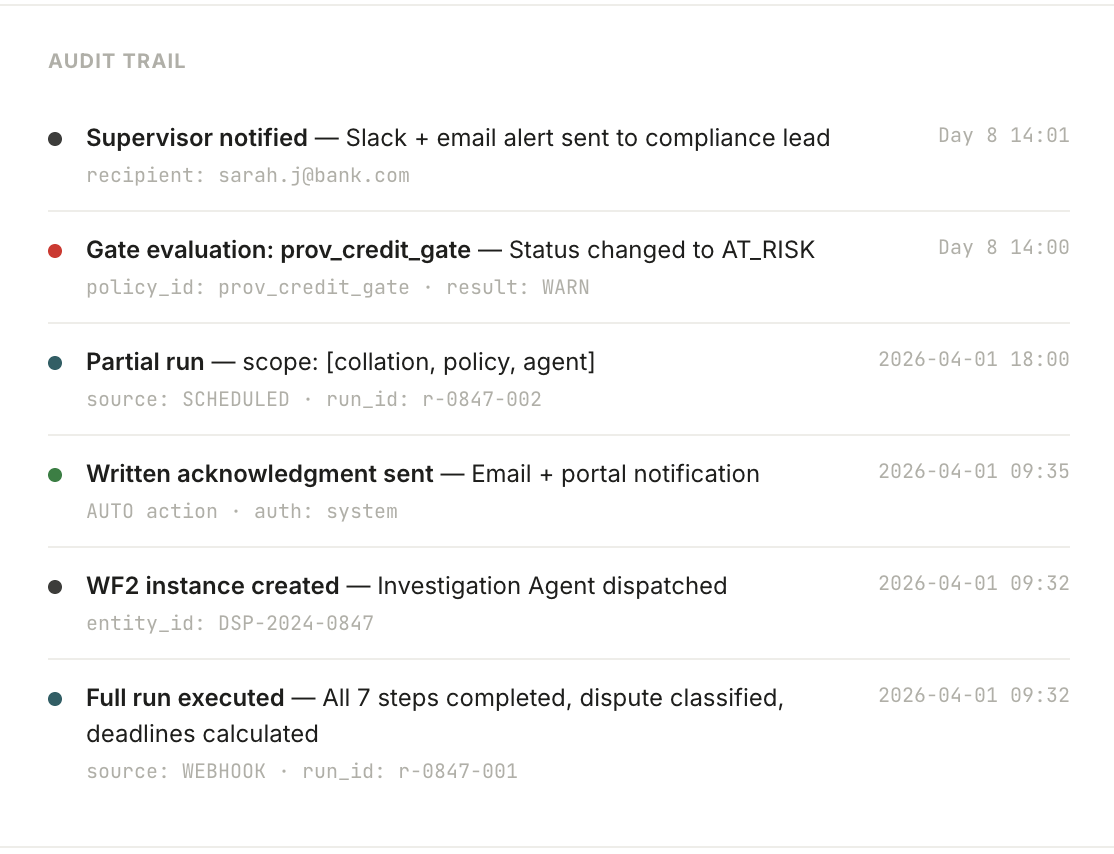
The pattern is the same everywhere. A reminder fires, someone is busy, the case sits, and by the time it is picked up the day-10 credit or the written explanation is late. Reminders describe the deadline; nothing enforces it.